

Most yoga teachers do not think about insurance until a student asks for proof of it, or until they are about to sign a studio contract that requires it.
The short answer: yoga instructors typically need professional liability (errors and omissions) insurance and general liability insurance, and most providers will not underwrite a policy at all unless you hold a recognised teaching credential. Annual premiums for independent instructors generally range from roughly USD 150 to USD 400, depending on class volume, location, and whether you teach hot yoga specifically.
What Insurance Do Yoga Instructors Actually Need?
Yoga instructor insurance is not one product. It is a small bundle of coverage types, and which ones you need depends on how and where you teach.
- Professional liability (errors and omissions). Covers claims that your instruction, cueing, or advice caused injury or harm. This is the core policy every teaching instructor should carry, employed or independent.
- General liability. Covers third-party bodily injury or property damage that is not directly about your instruction, such as a student slipping on a wet studio floor. Studios often require this before they will book a freelance teacher.
- Product liability. Relevant only if you sell mats, props, or branded merchandise directly to students.
- Property coverage. Optional, and mainly relevant if you own studio equipment, a heating system, or a home practice space you rent out.
For most newly certified teachers, professional liability plus general liability, often sold together as a combined policy, covers the realistic risk profile of teaching group and private classes.
Which cover do you need?
Start with the base policy, then add cover only for the situations that apply to you.
How Much Does Yoga Instructor Insurance Cost in 2026?
Cost depends on four factors: employment status, class volume, teaching location, and whether the style you teach involves added physical risk. Independent teachers pay more per hour of coverage than studio employees, because studios often carry a master policy that covers staff instructors. Entry-level annual premiums for solo instructors commonly start in the low hundreds of US dollars and scale up with the number of weekly classes and any specialised modalities, such as aerial or hot yoga.
| Region | Typical Annual Range (Independent Teacher) | Common Requirement |
|---|---|---|
| United States | USD 150 – 400 | Recognised teacher training (RYT or equivalent) |
| United Kingdom | GBP 100 – 250 | Yoga Alliance Professionals or equivalent registration |
| Indonesia / Bali | Highly variable, often bundled with studio or travel policies | Certification plus, in many cases, a local sponsoring studio |
These figures are representative starting ranges, not quotes. Always confirm exact pricing and terms directly with a licensed provider before purchasing, since underwriting varies by class format, student volume, and country-specific regulation.
Why Certification Comes Before Coverage
This is the detail most yoga instructor insurance articles skip: nearly every major provider requires proof of a recognised teacher training before they will issue a policy at all. An uncertified teacher is, from an underwriter's perspective, an unverifiable risk. This is why the sequence matters more than the shopping. Get trained and certified first, then coverage becomes straightforward to obtain.
Mr. Ian Terry, E-RYT 500 and founder of YogaFX, has seen this exact gap trip up graduates from less structured programmes: a teacher finishes a course, starts booking private clients, then discovers the insurer will not issue a policy because the training was not Yoga Alliance-registered.
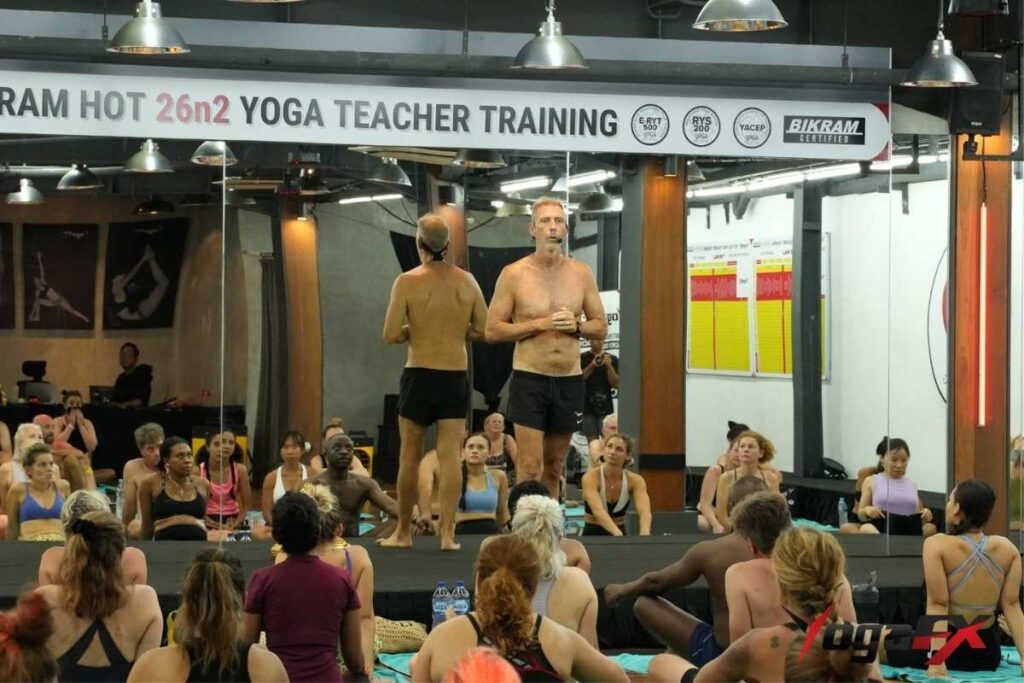
YogaFX's dual certification, an internationally recognised RYT 200 plus the Bikram Hot 26&2 credential, satisfies the registration requirement that most insurers ask for as a baseline condition, in the US, UK, and internationally. Current intakes are listed in our guide to Bikram yoga teacher training 2027 dates and cost.
If you are still weighing which RYT 200 certification path to take, insurability is a practical factor worth adding to the decision, alongside expected income once you are teaching.
Hot Yoga-Specific Risk Factors Insurers Look At
Generic yoga insurance guides rarely mention this, but it matters directly if you teach or plan to teach Bikram or 26&2 style hot yoga: heat-related risk is underwritten differently. A 90-minute class held at 40 degrees Celsius and 40 percent humidity carries a different liability profile than a room-temperature Vinyasa class, because heat exhaustion and dehydration are real, documented risks that a competent instructor is expected to actively manage, not just disclose.
Underwriters typically ask about room temperature protocols, hydration breaks, and whether the instructor delivers a scripted dialogue with built-in safety cueing rather than freestyle instruction, since a scripted method is easier to document as a consistent standard of care. This is one of the reasons hot yoga-specific training matters for insurability, not only for teaching quality: research on the format, including the 2025 Willmott et al. systematic review of 43 studies and 942 participants, has helped establish hot yoga as a well-documented practice category rather than an ambiguous risk, which in turn supports more predictable underwriting.
Do You Need Insurance If You Teach Online or Livestream Classes?
Yes, and this is the gap most yoga instructor insurance guides skip entirely. A student can strain a hamstring following your cueing over a livestream just as easily as in a physical room, and virtual liability claims are treated as real claims by underwriters, not as a lower-risk category by default. Several major providers, including Philadelphia Insurance and Next Insurance, now write dedicated coverage for on-demand video, livestreamed classes, and hybrid in-person plus virtual formats.
The practical difference is what the underwriter asks about. For in-person teaching, the questions concern the room, the props, and the floor. For virtual teaching, they shift toward whether you collect a signed waiver or informed consent from remote students, whether your on-demand library counts as a single class or an ongoing product, and whether you teach across state or country lines, which can trigger separate licensing questions.
If you teach both formats, confirm your policy explicitly names virtual and on-demand delivery. A general liability policy written only for in-studio teaching will not automatically extend to a livestream.
How Much Does Yoga Studio Insurance Cost?
A studio buys a different product from a solo teacher. Studio cover protects the premises, the business and every instructor teaching under it, so premiums are higher. Published industry benchmarks for 2026 fall into these ranges:
| Type of cover | Typical annual cost | Source |
|---|---|---|
| General liability only (USD 1M per occurrence, USD 2M aggregate) | About USD 350 | Insureon |
| Small studio, general liability | USD 400 to 1,200 | Wexford Insurance |
| Larger studio, general liability | USD 1,500 to 3,000 | Wexford Insurance |
| Business owner's policy (liability plus property) | About USD 700 | Insureon |
| Comprehensive studio package | USD 500 to 3,000 | Quotesweep |
Location, revenue, claims history and class type all move the price. Heated rooms and aerial rigs tend to push quotes toward the upper end of each range. These are benchmarks published by insurers and brokers, not quotes, so get two or three quotes for your own studio before you budget. If you are planning a studio of your own, see our guide to opening a Bikram yoga studio.
Studio insurance: typical annual cost (USD)
The same 2026 benchmarks as the table above, on one scale, so you can see where each type of cover sits.
Benchmarks published by Insureon, Wexford Insurance and Quotesweep, not quotes. Heated rooms and aerial rigs tend to sit at the upper end.
Coverage Limits, Occurrence Form and Certificates of Insurance
Limits. Every policy shows two numbers. The per-occurrence limit is the most the insurer pays for a single claim. The aggregate limit is the most it pays for all claims together during one policy term, usually a year. A policy written as USD 1M / USD 2M pays up to USD 1 million per claim and USD 2 million in total for the year.
Occurrence form vs claims-made. With an occurrence form policy, the incident must happen while the policy is active, but the claim can be reported later, even after the policy has ended. With a claims-made policy, both the incident and the claim must fall inside the policy period. Claims-made policies are usually cheaper, but if you cancel or switch provider you may need extra "tail" cover for claims that arrive later. For teachers who move between studios and countries, the occurrence form is the simpler choice (beYogi explains the difference).
Occurrence vs claims-made: when a late claim is covered
Same story in both cases: the incident happens while the policy is active, the claim arrives after the policy has ended.
Occurrence form
Only the incident must fall inside the policy period.
Claims-made
Both the incident and the claim must fall inside the policy period.
Claims-made policies are usually cheaper. For teachers who move between studios and countries, the occurrence form is the simpler choice.
Certificate of insurance. A certificate of insurance (COI) is a short document from your insurer that proves your policy is active. Studios, gyms, retreat venues and workshop hosts usually ask for one before they book a freelance teacher. It does not change your cover, it only evidences it. Some venues also ask to be named on your policy as an additional insured, so check with your provider whether that is included or costs extra.
Workshops and retreats. Before you teach a one-off workshop or a retreat abroad, confirm that your policy covers teaching away from your usual location and outside your home country. Many policies written for one country do not.
Choosing a Provider: US, UK and Bali Options
In the United States, providers such as Next Insurance and Berxi offer instant-quote policies aimed specifically at solo yoga teachers, while K&K Insurance and Philadelphia Insurance serve studio-level and higher-volume instructors. Membership through Yoga Alliance also unlocks access to partnered insurance benefits for registered teachers, most notably Alliant YogaPro, a professional and general liability bundle underwritten through Lloyd’s of London and offered at a member discount exclusively to Yoga Alliance registrants.
In the UK, Yoga Alliance Professionals-affiliated providers are the standard route, and most require proof of a registered training programme before quoting. In Bali and across Indonesia, dedicated yoga-specific insurance products are less standardised than in the US or UK. Most working instructors either teach under a studio's own liability coverage, which is why sponsoring studios matter for newly certified teachers, or arrange an international professional liability policy that covers teaching activity abroad. This is worth confirming directly with your studio or training provider rather than assuming coverage is automatic.
Graduates of the YogaFX hot yoga teacher training programme leave Bali with a credential that is recognised by insurers in all three markets, which removes one of the more common post-certification obstacles reported by newly qualified teachers. For a full picture of what the career path looks like end to end, see how to become a Bikram yoga teacher in 2026.
Checklist before your first paid class
The order matters: certification first, then coverage becomes straightforward.
FAQ
Do yoga instructors legally need insurance?
It is rarely a legal requirement in the way car insurance is, but most studios will not book a freelance instructor without proof of professional liability coverage, and it protects your personal assets if a student ever files an injury claim against you directly.
How much does yoga teacher insurance cost per year?
Independent instructors typically pay USD 150 to 400 per year in the US, or the GBP equivalent in the UK, depending on class volume and whether the policy includes hot yoga or other higher-risk formats. Studio employees are often covered under the studio's own master policy at no extra cost.
Does Yoga Alliance provide insurance for members?
Yoga Alliance itself is a registry, not an insurer, but registered members get access to partnered insurance benefits and discounted rates through affiliated providers, which is one more practical reason a Yoga Alliance-recognised RYT 200 matters when you are shopping for coverage.
Is hot yoga more expensive to insure than regular yoga?
Sometimes, modestly. Underwriters factor in heat exhaustion and dehydration risk, but a certified instructor who follows a structured hot yoga protocol, including scripted safety dialogue and set hydration breaks, is generally treated as a well-documented, insurable risk rather than a specialist exclusion.
Can I get insured if I trained through an online-only programme?
It depends on the provider and whether the training is Yoga Alliance-registered. Fully online programmes without any in-person practicum face more scrutiny from underwriters than hybrid formats that combine online coursework with supervised, in-person practice hours.
Do yoga teacher trainees need insurance during their training programme?
Most teacher training schools carry their own liability coverage for supervised practicum teaching, so trainees are not usually required to buy a separate policy while still in the programme. Once you graduate and start booking your own private clients or freelance studio slots, that school coverage no longer applies, and you will need your own professional and general liability policy from day one of paid teaching.
Are occurrence policies better for yoga teachers?
Usually, yes. An occurrence policy covers any incident that happens while the policy is active, even if the claim arrives years later. A claims-made policy is often cheaper, but you may need extra tail cover when you cancel or switch provider. For teachers who move between studios and countries, occurrence form is the simpler choice.
Is there insurance for part-time yoga teachers?
Yes. Premiums for solo instructors scale with how many classes you teach, so a few classes a week usually sits at the lower end of the typical US range of about USD 150 to 400 a year. If you only teach as a studio employee, the studio's master policy may already cover you, so ask before you buy.
What is the best type of liability insurance for yoga teachers?
For most teachers, a combined professional and general liability policy on an occurrence form. Professional liability covers claims about your instruction and cueing; general liability covers accidents such as a student slipping on a wet floor. If you also teach online or livestream classes, check that the policy names virtual teaching.